Yield Maintenance vs Step-Down Prepayment Penalty Structures
Early prepayment favors step-down; rising rates favor yield maintenance.
Prepayment penalties in commercial real estate exist for one reason: a fixed-rate lender is betting on a predictable income stream for the full loan term, and an early payoff breaks that bet. The lender has to take the returned principal and reinvest it wherever rates happen to sit that day, which might be well below what the original loan was paying. Yield maintenance and step-down penalties both exist to close that gap, but they do it in almost opposite ways, and this can swing the cost of exiting a loan by hundreds of thousands of dollars. Sponsors and brokers who don't know how each structure works are negotiating blind.
Which loan types carry which structure based on the funding source
The prepayment structure attached to a loan isn't really a negotiating point so much as a function of who's funding it. Fannie Mae and Freddie Mac multifamily loans commonly use yield maintenance, though step-down is also available on some agency executions, as do most life insurance company loans. CMBS loans typically use defeasance or yield maintenance depending on the deal structure.
Step-down penalties belong to a different world: bank and credit union portfolio loans, where the lender holds the paper on its own balance sheet rather than selling it into a security or a agency pool. Step-down is also sometimes offered as an alternative on agency multifamily executions, giving sponsors a real choice between the two philosophies on the same loan type.
CMBS conduit loans layer the restrictions on top of each other. A typical structure locks the loan out entirely for the first 24 to 36 months from origination, permits defeasance or yield maintenance for a window after that, and then opens up in the final months before maturity. That makes conduit debt the most restrictive prepayment environment in commercial real estate, full stop.
Life company loans cost somewhere in the middle. Many use yield maintenance tied to Treasury benchmarks, and terms vary by lender and deal. Generally, life company provisions carry more flexibility than what shows up in a CMBS pooling and servicing agreement.
The formula, variables, and factors that move the yield maintenance calculation
Yield maintenance, at its core, is a present-value calculation of lost income. The penalty equals what the lender would need today to make up for reinvesting the returned principal at the current Treasury rate instead of collecting the contract rate for whatever term remains.
The formula looks like this: YM = Σ [Monthly Payment × (Note Rate − Treasury Rate) / 12] / (1 + Treasury Rate / 12)^t, summed across every remaining month, where t represents each month in that string. Four variables drive the output: the note's contract rate, the matching-term Treasury yield at the moment of prepayment, how many months remain until maturity, and the outstanding principal balance.
The Treasury rate selection determines which benchmark applies and can significantly change the exit cost a borrower faces. Lenders match the benchmark to the remaining term of the loan. A loan with 36 months left uses the three-year constant maturity Treasury (CMT), not whatever index applied when the loan was five years from maturity. Some loan documents specify a different benchmark entirely, or tack on a spread above the Treasury rate, so the actual language in the note controls.
How interest rate direction turns yield maintenance from manageable to prohibitive
Rate sensitivity is what defines yield maintenance, and it's also what makes it unpredictable at the moment a loan closes. The penalty isn't fixed; it floats with Treasury yields for as long as the loan is outstanding. Nobody, not the borrower, not the lender, knows what it will cost to exit until the day they actually try.
When Treasury yields sit well below the note rate, the math turns brutal. The lender faces a real reinvestment shortfall across every remaining month of the loan, and discounting that shortfall back to present value compounds the number rather than shrinking it. A loan with several years remaining and a wide gap between the contract rate and prevailing Treasuries can generate a very substantial penalty on loans of significant size.
If the rate environment flips, the penalty collapses. If Treasuries rise to match or exceed the note rate, there's no shortfall left to replace: the lender can reinvest the returned principal at a rate equal to or better than what the loan was paying, so the yield maintenance premium falls to whatever floor the loan documents specify, such as the 1% floor common on agency loans. Two variables compound the size of the penalty in either direction: how much time is left on the loan (more remaining months means more shortfall payments to discount), and how wide the gap is between the note rate and the reference Treasury at the time of prepayment.
Why step-down penalties are the only exit cost known at closing
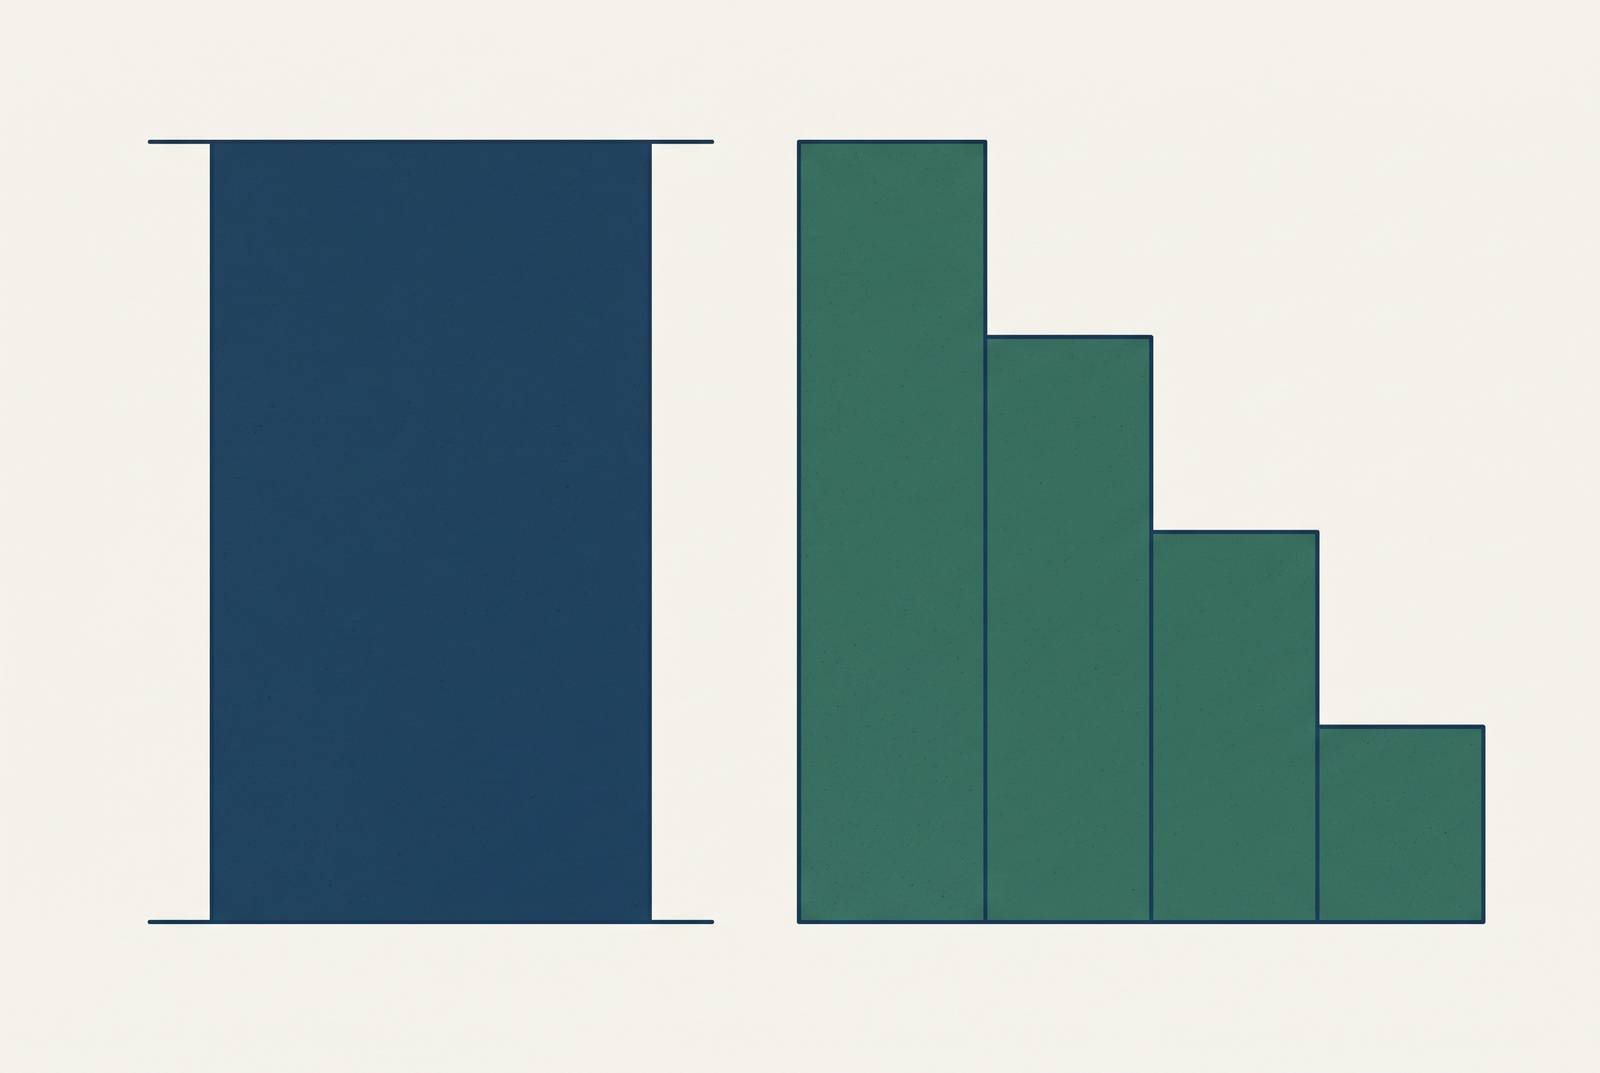
Step-down penalties, sometimes called declining or graduated prepayment penalties, work on a completely different logic. Instead of tracking a market rate, they apply a fixed schedule of percentages against the outstanding balance, and that schedule is written into the note at origination. It declines year by year as the loan seasons.
The classic version is the 5-4-3-2-1 schedule on a five-year loan: 5% of the outstanding balance if the borrower prepays in year one, 4% in year two, 3% in year three, 2% in year four, and 1% in year five. A common variant, the 3-1-1 schedule, only penalizes prepayment inside the first three years and drops to zero after that, with most lenders waiving the penalty entirely in the final 90 days before maturity.
Softer versions exist too. A 4-3-3-2-2-1 schedule, for instance, starts lower and steps down more gradually than a standard 6-5-4-3-2-1 ladder, giving borrowers an even gentler cost curve as the loan matures. Whatever the exact numbers, the defining feature of step-down is that it's entirely mechanical. The percentage in year three is written down in the loan documents at closing, and it doesn't move no matter what happens to interest rates between origination and payoff.
A direct comparison of when each structure costs more across scenarios
Neither structure is categorically cheaper. It depends entirely on where rates sit relative to the note rate at the moment of prepayment, and on how much time is left on the loan.
Early in a loan's term, when rates have fallen since origination, step-down tends to win by a wide margin. A $300,000 step-down penalty on a bank loan prepaid in year three looks modest next to a $500,000 or larger yield maintenance or defeasance cost on a comparably sized CMBS loan facing the same rate environment. That gap is not an edge case; it's the expected outcome whenever the differential between the note rate and current Treasuries is wide.
When rates rise past the note rate, yield maintenance can flip to the cheaper option. If the contract rate is at or below the prevailing Treasury rate, the yield maintenance premium falls to its floor, often just 1% of the balance, which can undercut whatever percentage a step-down schedule would still be charging in that same year.
Step-down's real advantage isn't that it's always cheaper; it's that it's always knowable. The penalty in year three is the same number whether Treasuries are at 2% or 6%. Yield maintenance in that same year could land anywhere from the floor to a seven-figure sum, depending entirely on where the bond market happens to be trading. Agency lenders make this tradeoff explicit at the term sheet stage: sponsors who accept yield maintenance get priced a lower interest rate, and sponsors who want step-down's certainty pay a rate premium for it. The right call depends on expected hold period and rate outlook, not on which formula produces a smaller number in a spreadsheet exercise.
How loan type, hold period, and rate outlook drive the prepayment structure decision
Hold period certainty is the first filter to run a deal through. A sponsor with a defined three-to-five-year exit and no room to extend needs to know the exit cost before signing anything, and step-down is the only structure built to deliver that number in advance. Yield maintenance simply cannot promise that, because its whole mechanism depends on wherever Treasuries land on the day of payoff.
Rate outlook is the second filter. Sponsors who expect rates to climb from origination are, in effect, watching their yield maintenance exposure shrink over time, since a rising-rate environment pushes the penalty toward the floor. Sponsors who expect rates to fall are accepting the opposite risk: potential penalty escalation the longer the loan stays on the books.
Loan purpose separates the two camps further. A value-add sponsor planning to stabilize and sell within a few years carries a very different risk profile than an operator planning a long-term hold, and the former is generally the one willing to pay a rate premium for step-down's certainty. The latter may prefer to trade that certainty away for the lower rate yield maintenance typically buys.
For CMBS and life company borrowers, though, this decision is often already made before the term sheet arrives. Yield maintenance or defeasance is baked into the structure, so the real question isn't which penalty to choose, it's whether the likely exit cost makes the loan worth accepting, and whether a future buyer assuming the existing loan is a viable path around triggering the penalty.
Why the $936 billion maturity wall makes prepayment structure literacy urgent in 2026
An estimated $936 billion in commercial real estate loans come due in 2026, representing a significant concentration of maturities across the near-term horizon. That volume of maturities is forcing thousands of sponsors into exactly the calculation this article has laid out, often on a compressed timeline.
For any borrower holding a loan with yield maintenance or defeasance provisions coming due, refinancing isn't automatically the obvious move. The penalty could eat materially into net proceeds, and the decision to refinance, extend, sell, or bring in fresh equity cannot be made responsibly without pricing the exact prepayment cost first.
Loans originated between 2014 and 2016, carrying coupons in the 3.5% to 4.0% range, are running into what's known as negative defeasance in the current environment. Because current rates sit above those legacy coupons, defeasing these loans can produce a net cash receipt to the borrower, something like 0.5% to 1.5% of the balance paid back rather than owed. Sponsors sitting on that vintage should model the defeasance math now, not after they've already committed to a refinance plan.
Lender behavior is also diverging in a way that matters for anyone facing a 2026 maturity. Lenders are tightening on maturing borrowers seeking extensions, holding firm to current underwriting standards even when the original loan wouldn't qualify today. At the same time, those same lenders are more accommodative toward new originations, competing for business from buyers who can meet today's standards. Existing borrowers who can't clear that bar face real resolution pressure, while new entrants find a lending market that wants their deal.
How purpose-built CRE technology closes the prepayment literacy gap
None of this math is exotic, but it is unforgiving of error, and doing it by hand across a loan portfolio, or across a single complex maturity, invites mistakes at exactly the moment precision matters most. The yield maintenance formula requires pulling the correct Treasury benchmark for the exact remaining term, matching it against the note rate, and running a present-value calculation across every remaining monthly payment, a process that leaves plenty of room for someone to grab the wrong CMT tenor or misjudge the payoff date by a month.
Purpose-built tools built for CRE underwriting and loan analysis close that gap by automating the inputs: pulling current Treasury data, applying the correct formula variant specified in a given note, and running the calculation against the actual remaining term rather than an approximation. For sponsors and brokers facing the current maturity wall, that kind of precision means knowing the real exit cost of a loan rather than guessing at it during a negotiation where the other side already knows the number.