Building a Referral Network for Commercial Mortgage Brokers
Structure networks around five partner types to capture 2026's refinancing wave reliably.
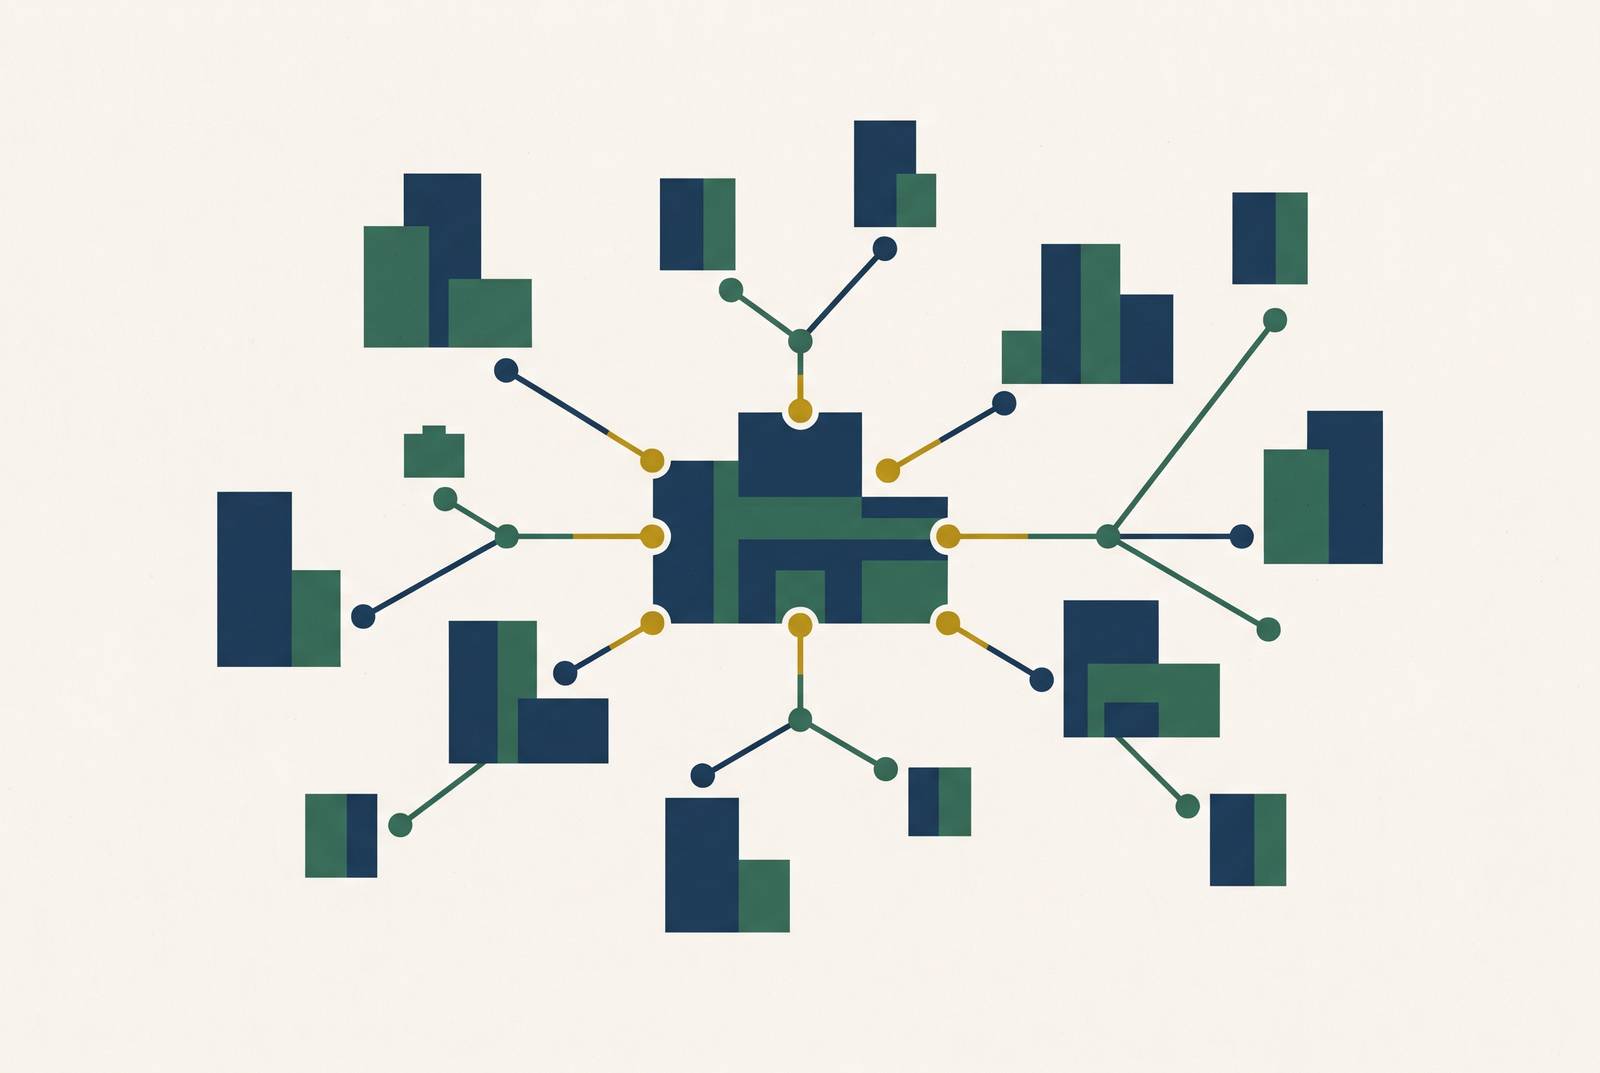
For commercial mortgage brokers, building a referral network means turning professional relationships into a deal pipeline they can count on. The strongest networks combine complementary partner types, clear specialization, regular contact, reliable execution, and measurable value exchange. In a market where origination activity and competition are rising together, relationships need that structure to become repeat business.
Why 2026 is the moment to build a structured referral network, not just tend relationships
A massive wave of commercial mortgages matures in 2026, creating refinancing demand as brokers enter the highest-volume origination environment in years. Sponsors facing maturity need financing, and brokers with active partner pipelines are positioned to hear about those needs first. More volume does not make it easier to find clients. Competition intensifies as more brokers pursue the same sponsors and lender relationships, making early introductions particularly valuable.
AD Mortgage’s broker survey found that strengthened referral networks were among the factors brokers credited for their growth outlook. The same survey found that a third of brokers still cited client acquisition as a problem. A structured network gives a broker a repeatable route to borrowers rather than leaving the next transaction dependent on an informal introduction.
Why referred deals outperform every other lead source in commercial mortgage brokerage
Referred deals have higher conversion rates and lower acquisition costs because trust is already in place when the introduction is made. In a commission-based referral arrangement, the acquisition payment follows a closing rather than preceding an uncertain response, as advertising spend does. The economics favor completed transactions over speculative attention. That distinction gives referral-first growth an advantage before the broker considers the quality of the borrower.
Lenders are scrutinizing sponsor experience and cash flow quality, so an introduction from an accountant, attorney, or equity partner has a different starting point from a cold inquiry. It places the borrower in a professional context that a cold inquiry lacks while leaving lender underwriting in place. Word of mouth is especially influential in large, infrequent, high-stakes decisions, which makes commercial mortgages particularly well suited to this model.
The five partner types that generate the highest-quality CRE deal flow
Commercial real estate brokers and investment sales teams work directly with buyers who need financing for acquisitions. Brokers who handle deals regularly are especially valuable, since a single active investment sales agent can send referrals every month. The exchange works in both directions. A mortgage broker who pre-qualifies buyers helps the sales broker bring more closeable transactions to the table.
CPAs and tax advisors identify financing needs through conversations about investment property, depreciation strategy, and tax-advantaged real estate. Their high-net-worth clients often have self-employed income or partnership structures that need a specialist’s help. Complexity creates the opening for a commercial broker. Hosting educational events together can also help both professionals meet clients through someone they know and show what they know.
Financial planners and wealth managers hear about financing needs when clients move from talking about portfolio allocation to buying commercial property. The broker knows how to work with complex borrower profiles, including foreign income, portfolio lending, and entity structures. Reciprocity gives this relationship a practical foundation. The planner sends clients who need capital to the mortgage broker, who in turn sends clients who need wealth management to the planner.
Commercial attorneys provide access at different points in a property’s ownership cycle. Transactional attorneys see acquisitions and dispositions, estate attorneys handle wealth transfers involving real property, and entity attorneys structure the LLCs and partnerships that own CRE assets. These relationships are often cultivated less systematically by mortgage brokers. Discretion is the central value offered in return, because attorneys need confidence that complex client situations will be handled sensitively.
Other commercial mortgage brokers provide complementary expertise. A multifamily bridge specialist may encounter an SBA 504 financing need, while a broker in a neighboring market may need help with an expanding sponsor. Structured referrals preserve opportunities that would otherwise be lost. Together, these five partner types diversify deal flow across transaction activity, financial advice, legal work, and specialist brokerage.
How to make first contact with a potential partner in a way that earns the relationship
To activate these relationships, the broker should lead with useful work. The first week’s contribution can be a suitable referral, practical market intelligence, or help with a partner’s financing problem. The opening establishes the terms of the relationship. Giving something useful before reciprocity exists makes the conversation collaborative.
A practical 30-day activation sequence begins by identifying active professionals across the five partner categories and finding where they already gather. Commercial real estate association meetings, investment forums, and gatherings of legal and financial professionals are better places to meet these partners than general business mixers. LinkedIn extends that contact between meetings. Connecting with relevant professionals, sharing CRE intelligence they can use with clients, and responding consistently to their content creates continuity without relying on a sales pitch.
The remaining work is to turn contact into a specific exchange. A sales broker may want help with buyer pre-qualification, while an accountant may need help with a complex borrower profile. The first referral given demonstrates commitment more clearly than a promise of future business. This sequence need not take years to become operational and can establish a working relationship faster than most paid lead channels take to optimize.
What specialization does to the value of a referral and why generalists lose it
Specialization gives a partner a precise reason to make an introduction. A broker known for transitional multifamily bridge loans occupies a different place in a partner’s thinking from one known for SBA 504 financing for owner-occupied commercial property. Each specialty defines a recognizable financing problem. When partners know which financing problems a broker handles, they can send their most complex clients to someone with the right skills for the deal.
Generalism weakens that connection because a broad description offers little guidance about when to call. A bridge-to-perm execution on a value-add multifamily property is a specific referral cue, while an offer to handle all commercial loans is not. The specialist’s expertise reaches the borrower before the introduction. That prior endorsement can compress the sales cycle and improve close rates without making the broker compete solely on rate.
The apparent trade-off is a smaller addressable market. Yet a deep partner network within one niche can produce more closed deals than a shallow network spread across many specialties. Concentration strengthens both recognition and referral quality. Additional niches can follow once the first is established, rather than blurring the broker’s position from the outset.
The touchpoint cadence and CRM structure that keeps partners active
Referral networks often decay because contact is undocumented and irregular. A partner eventually sends the next borrower to the broker who is most recently top of mind. A calendar prevents that avoidable loss of visibility. MGIC’s Loan Originators Survey Report found that weekly contact was the most common frequency among loan originators, although that finding is not a CRE-specific schedule.
For a commercial brokerage, a practical cadence gives top partners at least monthly contact through a market update or deal insight. Quarterly in-person meetings provide space to discuss financing needs, while milestone acknowledgments recognize anniversaries, closings, or business news. An annual business review completes the cycle. Immediately after a referred transaction closes, a thank-you call connects the outcome back to the relationship.
Communication during the transaction is equally important. Brief updates when a term sheet is issued, an appraisal is ordered, or the borrower reaches clear to close reassure the referring partner that the client is being handled well. Co-branded market updates, deal structure explainers, and lender landscape summaries extend that value to the partner’s clients. In the CRM, a previously active partner who sends no referral for 60 days should trigger an automatic outreach reminder, turning inactivity into a defined follow-up task.
How to structure referral compensation to keep partners motivated and stay compliant
Where legally permissible, written compensation terms make value exchange explicit and reduce uncertainty about payment. Broker-to-broker arrangements commonly use basis points of the loan amount, which scale compensation with transaction size. Another structure allocates 15–25% of the origination fee. Both connect compensation to the completed deal, but neither is automatically permissible simply because the parties agree to it.
The appropriate action is legal review before formalization. Arrangements with real estate brokers, attorneys, or other settlement service providers should be reviewed with a compliance attorney. Broker-to-broker referrals and relationships with financial advisors, accountants, or equity partners require analysis specific to state licensing rules. A partner’s line of work alone does not free them from the referral restrictions that apply.
RESPA compliance also governs how legitimate collaboration is distinguished from payment for introductions. The CFPB states that there is no exception to Section 8 solely based on the value of a gift or promotion. Payments for co-branded marketing must be in proportion to the fair market value of services that are actually performed and must not depend on referrals. Charging a market rate alone does not make an arrangement legal. Educational events and content collaboration must also offer real value, with each partner’s effort and cost in proportion to their share, and must not hide payments for referrals.
Once a lawful arrangement is established, the broker should document it and pay promptly. Partners left waiting months for an agreed commission have less reason to send the next transaction. Prompt payment becomes part of the broker’s reputation. A partner paid within a week of closing experiences a different standard of reliability from one who must repeatedly pursue compensation.
How AI tools are changing what a commercial mortgage broker can offer a referral partner
A referral partner lends professional credibility to an introduction, so execution quality is part of the value exchange. Clean, AI-structured loan packages can reduce lender follow-up requests and support faster closings. The operational bottleneck is often financial preparation. Manually converting an offering memorandum, rent roll, and T12 into a populated underwriting model can take four to eight hours per deal, delaying lender response and frustrating borrowers.
AI agents are being deployed to automate that sequence. Intake agents produce structured summaries and missing-items lists, while document agents create auditable indexes. Spreading agents extract and normalize financials. Underwriting agents then draft memo-ready narratives with linked evidence, allowing the steps to run without manual handoffs. The relevant distinction is not the presence of AI but whether the resulting package helps the transaction move efficiently.
Tools for prospecting, marketing, and transactions that do not connect can still slow that work by making it hard to keep the same information across them. A unified platform addresses that fragmentation across the workflow. Referral partners see the outcome. Faster loan preparation, cleaner submissions, and proactive status communication make the introduction reflect well on them and give them a concrete reason to refer again.
Measuring whether your referral network is actually working
A useful record for each partner tracks referral frequency, referral quality, deal size, and partner-to-close cycle time. Frequency shows whether a source remains active, while quality measures the share of referrals that reach term sheet or closing. Low quality can reveal unclear niche positioning. Deal size indicates whether trust is deepening enough for the partner to introduce larger transactions, and cycle time shows how efficiently the brokerage converts an introduction into a completed loan.
Measuring the whole network helps show whether referrals are growing or the market as a whole is growing. The target is a rising referral share of total deal volume while total volume also increases. A larger share alone is not enough. Once per year, ranking partners by the deals they bring in helps the broker decide how much time to spend reaching out to those who bring results.
When a partner’s volume declines, touchpoint records provide the first diagnostic evidence. Contact may have become less frequent, the broker’s niche may have changed without explanation, or the partner’s own business may have shifted. Measurement becomes useful when it triggers a response. The 60-day inactivity reminder, quarterly relationship review, and annual partner tier rebalancing help brokers keep up with the network when they are busy closing deals.
Those checks and follow-ups turn staying in touch into a referral system. Brokers who build and measure that system in the current market are developing a durable competitive advantage.