The Capital Markets Desk Workflow for Compressing Raw Financials Into a Lender-Ready OM
Analyst-owned reconciliation converts raw deal folders into defensible, lender-ready packages.
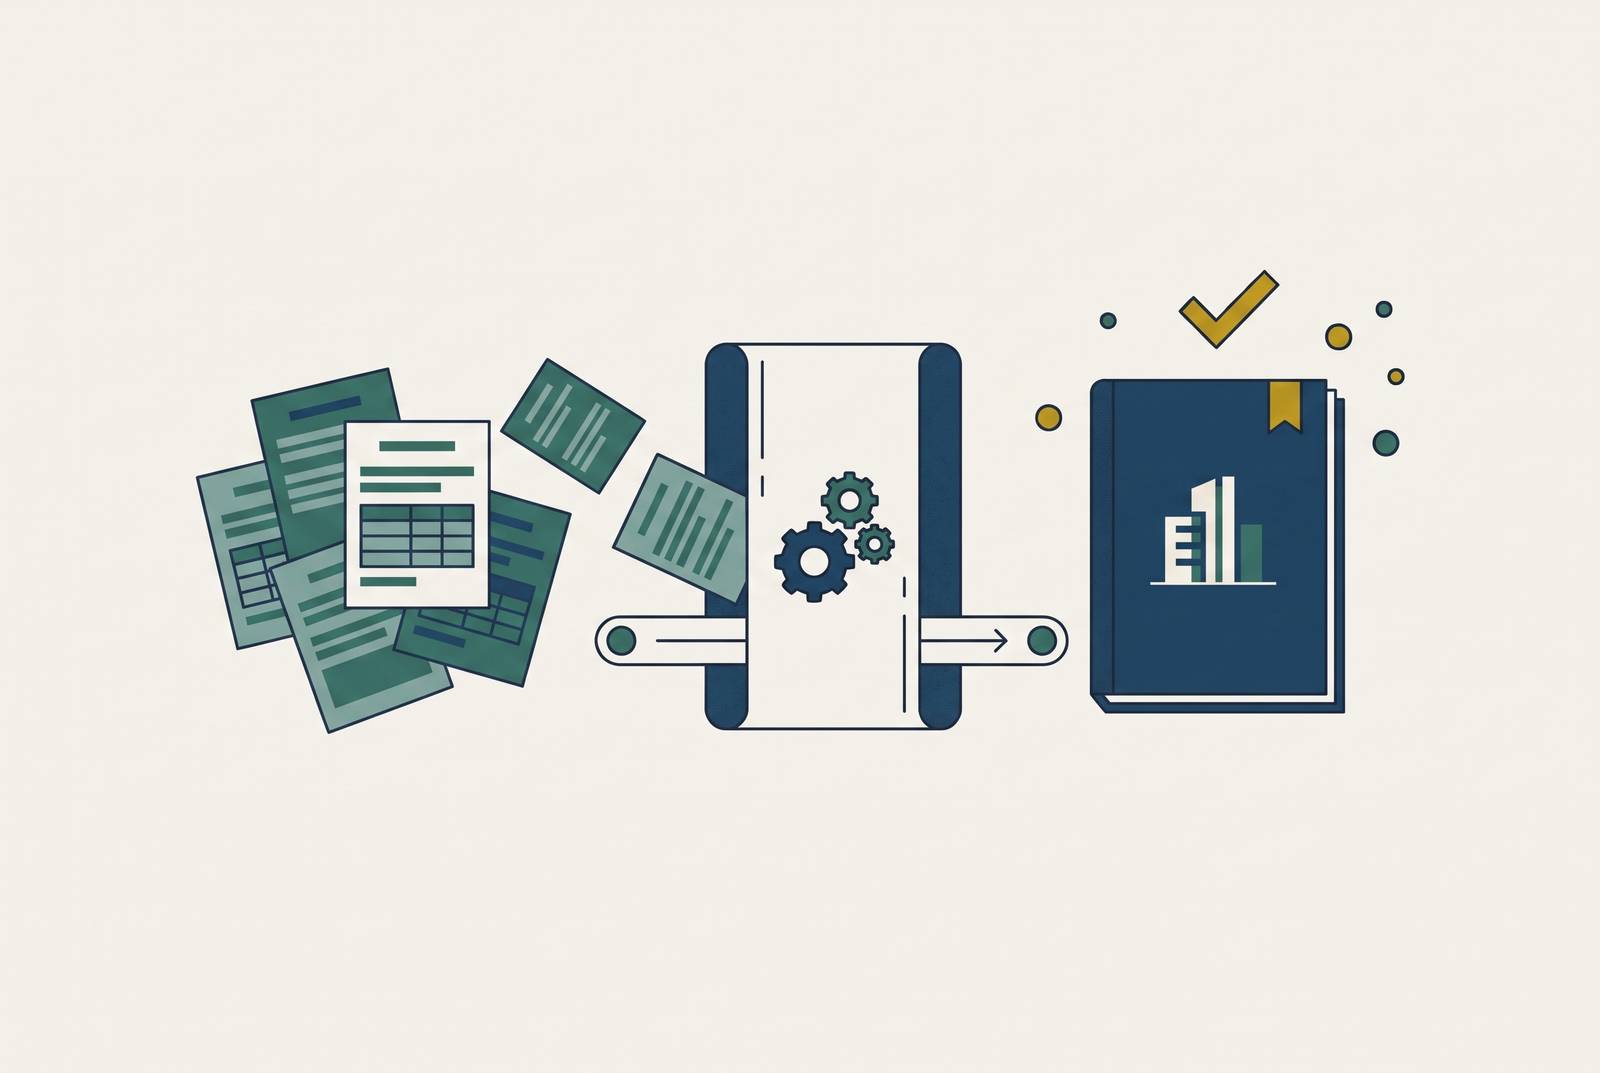
Automated CRE offering memorandum and loan memo generation can compress document extraction and drafting, but a lender-ready package still requires analyst-owned underwriting and reconciliation. The capital markets desk workflow separates those tasks into discrete, learnable steps, from raw financials to a defensible credit narrative. Purpose-built CRE tools earn their place when they offer source traceability, current market data, and internal consistency along with faster prose.
What the capital markets desk workflow actually is — and what it is not
A seller-marketing OM leads with the investment thesis, photography, and marketing narrative. A lender-ready OM leads with cash flow stability, collateral quality, and repayment capacity because its purpose is a credit decision. That distinction determines which evidence receives priority. A persuasive property story cannot substitute for an explicit financing request or support for the income available to service debt.
The lender-facing document must answer, in order, what the loan request is, what the asset cash-flows, who the sponsor is, and what the market supports. The sequence serves the lender’s decision process. But the work may follow a different order because the executive summary needs the finished analysis. This is a defined conversion process rather than an open-ended creative assignment, with a raw deal folder at one end and an internally consistent package at the other.
The raw deal folder: what arrives on the desk and what it contains
The package that arrives usually has an offering memorandum prepared by the seller, a trailing-twelve-month operating statement, a rent roll, and lease agreements or abstracts. The seller’s OM sometimes has assumable debt terms or other financing details. PDFs, Excel files, and scanned images do not share a common structure, so the composition of the folder determines the extraction burden before analysis begins.
The rent roll also does not contain every economically relevant lease term. Renewal options, free-rent periods, and fixed-dollar rent bumps versus compounding escalations may be embedded in the underlying agreements. The lender-facing executive summary and sponsor profile require the analyst to develop the underlying material into new sections. Intake therefore establishes both what can be extracted and what must be developed.
Document ingestion: extracting structured data from unstructured sources
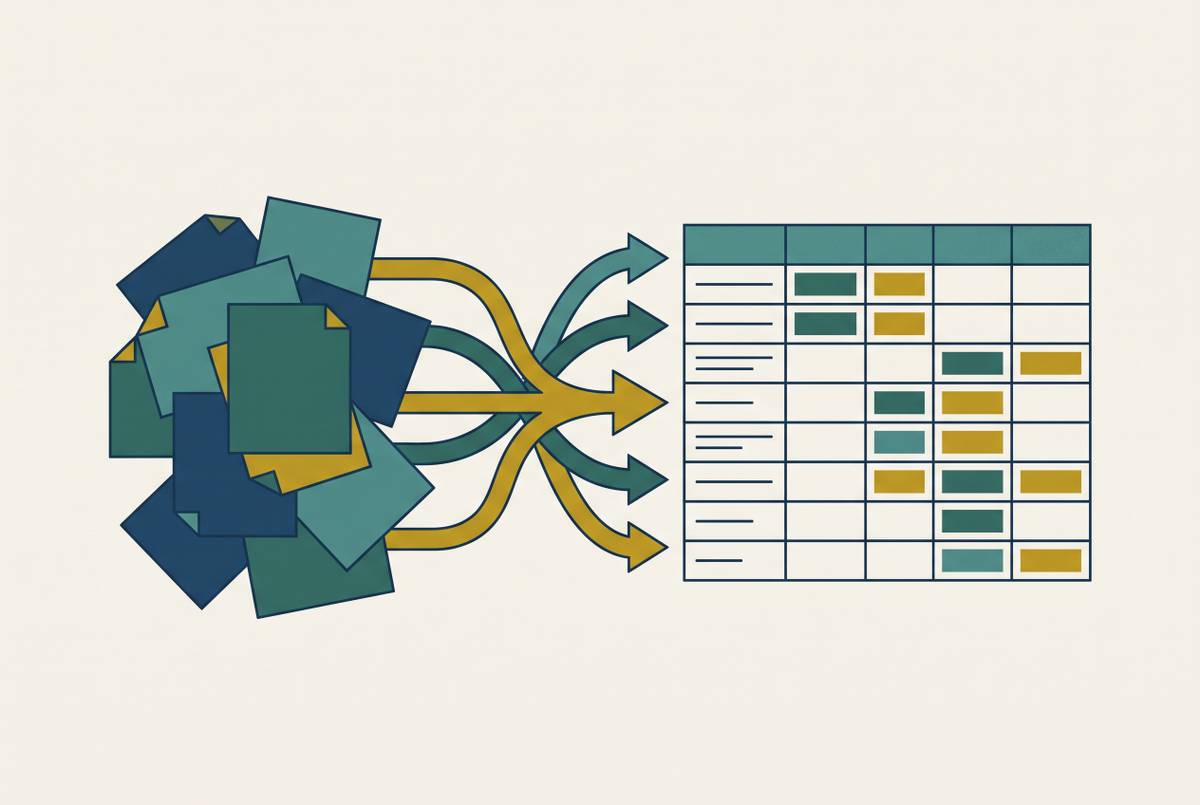
Document-to-model ingestion turns that heterogeneous folder into structured data for the financial model. It is the highest-cost manual step on most capital markets desks, consuming hours in locating tables, transferring figures, and aligning information across documents. The work precedes the actual underwriting judgment. Extracting an expense amount does not establish whether the expense is recurring, and finding an escalation clause does not establish its correct financial treatment.
Document extraction can cut the work of moving data by hand, but the analyst still owns the assumptions used afterward. A well-implemented workflow also connects every extracted number to its source page, giving the analyst and lender an auditable lineage. Traceability is a required part of the output. Structured data without that connection may be easier to model, but it is harder to defend when a lender questions a figure.
Spreading and normalizing the financials: from raw numbers to defensible NOI
Financial spreading converts the T-12 into a model that distinguishes recurring from non-recurring income, controllable from non-controllable expenses, and in-place results from pro forma assumptions. Each classification changes how the property’s earnings are understood and can become a point of disagreement with a lender. Normalized NOI must therefore reflect a defensible treatment of the source financials rather than merely reproduce the seller’s presentation.
Revenue projections need market rent analysis and realistic absorption, while expense forecasts must account for what drives costs at the property and for inflation. Exit assumptions require support from cap rate trends and comparable sales. IRR, equity multiple, cash-on-cash, and yield on cost are outputs of the spread model, whose assumptions require separate support.
Lease interpretation is the highest-risk part of this step and a frequent source of downstream objections. A fixed-dollar rent bump must not become a compounding escalation, while free-rent periods affect the effective rent schedule and renewal options affect the expiration profile. An NOI error then reaches DSCR, calculated as NOI divided by annual debt service, and debt yield, with consequences for the financing analysis.
Building the financial summary the lender actually uses
The financial summary presents the spread financials as evidence a lender can assess. It receives the closest scrutiny because it connects property performance to the proposed financing. Presentation cannot repair a weak underlying model. Its purpose is to make the cash flow, assumptions, and financing implications accessible without introducing a separate version of the underwriting.
A suggested financing scenario table is a useful addition that many broker-built OMs underdevelop. It should show several LTV bands with indicative coupons and DSCR so lenders can benchmark the deal against their own capital stack before a call. That comparison can compress the first round of financing conversations. But the scenarios must use the same financial basis as the rest of the OM. Consistency between the summary, supporting exhibits, and loan request is a quality-control requirement.
Market analysis: what the section must establish and where the time goes
The market section supplies external support for the deal’s internal assumptions. Lenders will independently know the market, making stale or unsupported data an immediate credibility problem. Adjustments for property condition, location, and transaction timing distinguish a supported comparison from a marketing exhibit.
Producing that evidence takes a substantial block of research time. The work includes pulling data, reviewing recent transactions, calling brokers for off-market intelligence, and synthesizing the findings into a coherent narrative. Retrieval is only part of the production cost. Population data, daytime employment, and radius-ring maps may be publicly available, yet collecting, formatting, and rendering them still consumes analyst time. AI tools can do that work so the analyst can spend more time making sense of the data.
The failure mode is not simply missing information. A polished market narrative can still rest on stale inputs or comparisons that do not support the stated conclusion. Its apparent completeness therefore does not establish its evidentiary strength. The section earns its place by supporting the underwriting with current, relevant information rather than surrounding the financial summary with generic market description.
Sponsor profile and loan request: the two sections most brokers underwrite last and underwrite least
The sponsor profile completes the credit picture beyond the asset. Lenders underwrite the sponsor as well as the property, so a generalized or buried profile leaves a required part of their decision underdeveloped. The loan request has a similarly precise purpose. It must state the proposed financing clearly enough that the lender does not need another exchange merely to understand what is being requested.
These sections are often assembled late and too quickly. The resulting gaps create avoidable lender friction on the path to a term sheet. Moraine’s IC memo guide distinguishes an acquisition IC memo, a broker’s OM, and a lender’s credit memo by their readers and evidence requirements. Reusing a format without respecting those differences produces the wrong emphasis, even when the underlying property information is accurate.
Assembly and internal reconciliation: the step where errors become permanent
Assembly joins sections that were developed on their own into one credit package. It is the gate where inconsistencies are either resolved or included in the lender’s final document. Formatting is only one part of that work. A narrative built around an earlier assumption can conflict with an updated exhibit even when both sections appear complete on their own.
CREbuilder’s OM guide places the work in a production sequence that begins with property data and financials, then adds location, demographics, tenant profiles, and investment highlights before the cover and executive summary. It places the numerical tie-out before export. The executive summary is written last for a reason. It summarizes the completed document rather than establishing claims that unfinished analysis must later accommodate.
Moraine’s guide also warns against divergence between the prose, spreadsheet exhibits, and underlying source package. Each material statement of fact needs a document it can be traced to or a named source, and when assumptions change, the affected narrative and tables must be reconciled before the package is sent out. This is where rigor becomes a release condition. An error that survives assembly is no longer confined to a working file but reaches the lender as part of the submitted case.
Where the workflow actually loses time — and what that reveals about where rigor lives
Extraction, data entry, formatting, and repeated transfer absorb hours before the analyst reaches the questions needed to defend the deal. Time spent moving rent-roll data leaves less time for interpreting the leases behind it.
That imbalance explains why a labor-intensive process can still produce weak underwriting. Manual effort is not itself a quality control. An analyst can spend substantial time recreating source information while having too little time left to validate assumptions or stress-test the model.
Rigor resides in the judgment-bearing steps, including lease interpretation, NOI normalization, assumption validation, and cross-section reconciliation. Automation changes the allocation of work while judgment remains necessary. Without a human review gate, faster preparation can simply give an upstream mistake more opportunities to propagate.
The verification pass: what the analyst must own regardless of how the draft was produced
The strongest objection to AI-assisted production is real. Automated workflows can propagate an error faster and less visibly because each downstream step inherits the upstream output. Lease structures are a particular risk, since a systematic misreading creates errors across the cash-flow schedule. Stale or inconsistent inputs create the same problem across agentic workflows, increasing the correction burden as subsequent work builds on them.
The response is a defined verification pass, regardless of how the draft was generated. The analyst must confirm that every extracted number traces to its source page and verify lease interpretation at each escalation and option. Review then reconciles NOI across sections and checks that the loan request matches the financial summary’s implied structure. Market data citations must also be current. Together, these checks test both the underlying evidence and the consistency of its use.
Uncertainty needs explicit treatment during that review. Moraine’s guide separates a stated lease term from the analyst’s interpretation of its financial effect and advises leaving lease status open when the documents do not establish it. It also calls for a disposition for every material issue rather than hiding unresolved exceptions in an appendix. For a lender-ready OM, that means a confident summary cannot erase an unresolved underwriting question.
What should AI tools for CRE loan memo generation add beyond general assistants?
General AI assistants such as Claude and ChatGPT can produce a first draft quickly when supplied with the right documents. That makes them useful for drafting, but drafting alone does not complete the capital markets desk workflow. In general-purpose use, live CRE data connections, a lender-ready format, and checks for lease-escalation misreads cannot be assumed without explicit setup and instructions.
The practical test is whether a tool can trace extracted numbers to source pages, enforce internal consistency across sections, and connect to current market data without a manual export step. Those are concrete capabilities a buyer can assess. They also distinguish a reusable loan-memo workflow from a fast first draft that still requires the analyst to reconstruct its evidence.
The notes establish no vendor-specific basis for ranking those capabilities, so a named “best” tool would overstate the available evidence. The defensible comparison is between drafting assistance and support for the complete production sequence. Neither category removes the analyst’s verification responsibility. The useful measure of automation is how much transfer and reconstruction it removes while preserving the review required for a lender-ready decision package.