Systematizing the CRE Loan Memo so Capital Markets Teams Stop Rebuilding the Wheel Each Closing
Systematizing loan memo data cuts manual rebuilding and speeds underwriting.
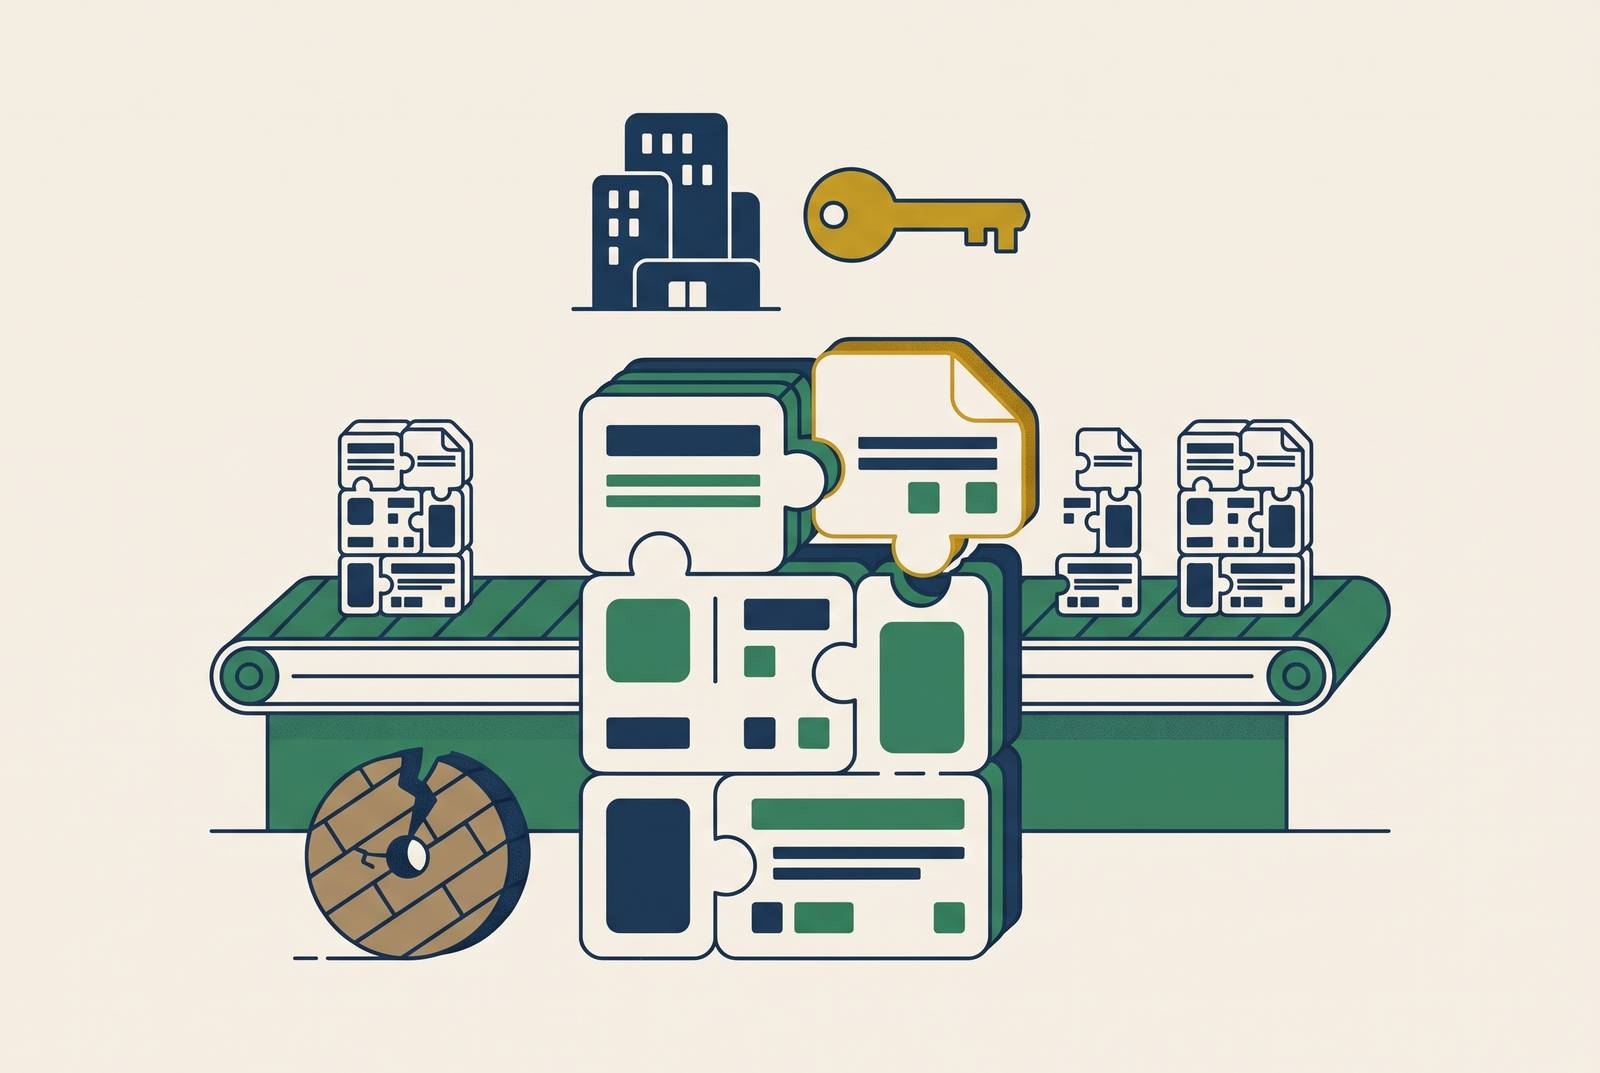
A lender-ready CRE loan memo starts with a reusable framework that connects defined source documents to consistent financial fields, loan-type modules, and underwriter-written credit analysis. AI-powered extraction accelerates that framework by removing manual re-entry while preserving credit judgment. Systematizing the memo is therefore a capital markets infrastructure decision, enabling teams to execute faster, present more credibly, and win more mandates in a high-volume, selective market.
Why 2026 origination volume is straining manual memo workflows
CRE origination activity is accelerating as deferred maturities create additional refinancing and restructuring work. The Federal Reserve’s January 2026 Senior Loan Officer Opinion Survey found that banks began easing CRE underwriting standards for the first time since 2022. That shift signals a new origination cycle. Invesco Real Estate, using MBA data, reports that private non-bank CRE lenders’ share of total originations roughly doubled after the pandemic compared with the prior decade. More types of lenders are competing for deals, so speed in getting them done matters more.
Loans deferred from 2024 and 2025 now require restructuring, fresh capital, or workouts, each generating underwriting work beyond new originations. Capital availability alone cannot resolve that workload. Teams must handle more transactions while lenders look at each asset class on its own, stress-test rate scenarios for each property, and price risk more precisely. Easing underwriting standards and greater selectivity can therefore coexist, because renewed willingness to lend does not mean equal appetite for every property. The immediate constraint is operational capacity to support that discrimination at higher volume.
Where the manual memo process actually breaks down under deal pressure
The manual workflow proceeds through sequential handoffs from receipt to underwriting, memo preparation, committee review, and term sheet. At receipt, source documents arrive in different formats. Underwriting turns those documents into financial calculations, which memo preparation then transfers into another deliverable. Committee review depends on the accuracy and consistency of that transfer before the transaction can advance. Each handoff becomes a bottleneck when the next participant must reconstruct what the previous participant assembled.
Credit, legal, and closing stakeholders may work from different memo versions, allowing discrepancies in LTV or DSCR calculations to enter credit decisions. Even within one version, a figure in the deal summary may conflict with its counterpart in the financial section. The same information exists in several places without a single controlled source.
That fragmentation persists after the initial closing. A loan is underwritten at origination, extension, quarterly review, and refinancing, yet each pass can begin again with source documents that never share a format. The prior memo provides something to read, but not necessarily structured information to reuse. As volume grows, this repeated reconstruction consumes the capacity needed for new transactions and prevents the memo from accumulating institutional value.
Why a disorganized memo package is disqualifying before underwriting begins
Figures that conflict or a package with missing pieces signal execution risk, making the lender doubt the transaction’s readiness for review. Presentation becomes evidence of the team’s control over the deal. For sponsors and brokers, that signal can undercut otherwise strong in-place cash flows, creditworthy tenancy, and experienced sponsorship. A package that requires reconciliation before analysis can be effectively disqualifying in a selective market.
The OCC’s FY 2025 Supervision Plan focuses scrutiny on concentration management, documentation of collateral values and credit utilization, and maturity and renewal exposures. The OCC Comptroller’s Handbook requires credit ratings to be supported and documented in the credit file, with a clear audit trail for approvals. Lenders without standardized records face duplicated analyst effort at extensions and quarterly reviews, while documentation gaps expose them to audit findings.
Sponsors and brokers who send complete packages with figures that agree each time get processed faster and build relationships with lenders more quickly. Repeat mandates follow from that pattern of execution. Teams that send disorganized packages leave lenders with more work to do before they can assess the credit. As lenders become more selective, the gap between those counterparties widens.
What it means to treat the loan memo as infrastructure rather than a document
A document is produced, delivered, and filed. A governed data object retains structured fields that can be reused, traced to their inputs, and presented consistently across deals using the same framework. The memo becomes an output of that structure. This distinction changes what survives a closing. The team retains not just the finished narrative, but the organized financial and structural inputs needed for the next review.
In practice, the framework has a fixed section architecture covering the deal summary, collateral description, borrower and guarantor profiles, financial spreading, market context, risk factors, and credit recommendation. Financial spreading includes NOI, DSCR, and LTV. Each financial field has a defined source, such as a rent roll, T-12, appraisal, or tax return. Figures entered once propagate across the relevant sections. Construction loans, bridge deals, permanent financings, and portfolio transactions use modules within that common architecture, eliminating the need to rebuild separate documents from scratch.
Using the same format also helps teams assess the whole portfolio as well as present each deal. The joint CRE trade letter to federal regulators describes Basel III capital framework proposals involving granular LTV- and cash-flow-based risk weights. Those proposals reinforce the need to document LTV, cash-flow dependence, lien position, and loan structure in a consistent, auditable format. Those proposals remain distinct from the requirements in place today. Nevertheless, the underlying infrastructure need is clear, because reconstructing the same loan characteristics deal by deal obstructs a coherent portfolio view.
How to create a lender-ready CRE loan memo without starting from scratch
The practical task is to decide what stays fixed, what remains flexible, and where human judgment enters the framework. Fix the section structure, field labels, and narrative order so lenders and credit officers can navigate each memo without learning a new layout. Keep the content within those sections flexible. The underwriter still handles risk commentary, market context, and sponsorship assessment. The template determines where the analysis belongs.
Define the input-to-field map before building the template. Trace every financial figure to exactly one source document and one extraction method, including the relevant T-12 or rent roll vintage. Source ambiguity is already a version-control failure. Automate rent roll ingestion and financial extraction when documents arrive to cut low-value data entry before work on the memo begins. This decision establishes which information enters each field before formatting choices obscure unresolved input questions.
Build modules for each loan type within the same framework. The common architecture should accommodate the draw schedule, cost-to-complete, and completion risk sections specific to construction loans. Preserve data continuity for participations, cross-collateralization, and mezzanine structures so servicing teams do not have to rebuild loan structures manually from a PDF memo.
Design the same structure for the full loan lifecycle. Make the prior memo the structured starting point for extension, quarterly review, and refinancing, eliminating the need to reread it and re-enter its information. Keep post-close DSCR, occupancy, and covenant monitoring within the same data architecture. Origination and monitoring should not become separate information systems. This decision allows subsequent reviews to draw on established fields while the underwriter reassesses the credit.
What AI-powered extraction actually changes in the memo assembly process
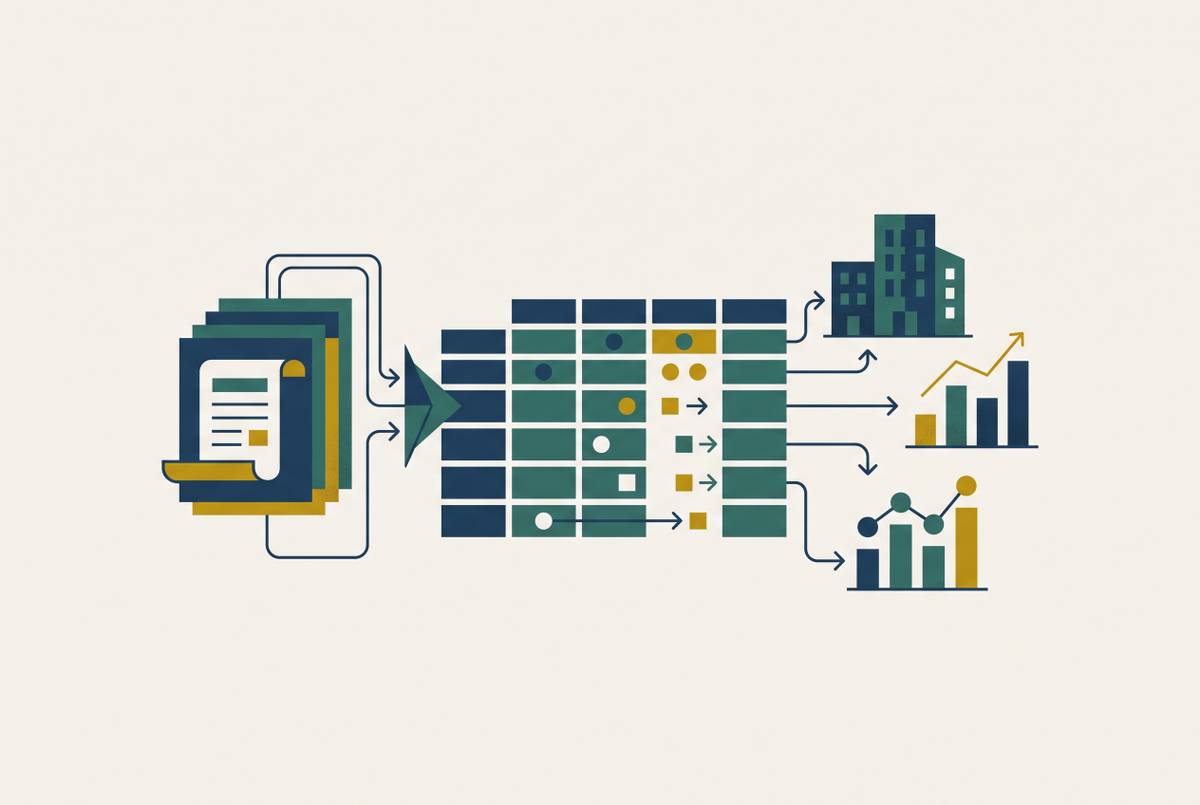
AI-powered extraction addresses the point where manual assembly consumes analyst time and introduces transcription errors. At intake, it parses offering memorandums, rent rolls, T-12s, appraisals, and leases, then maps relevant information to predefined input fields. The input map gives extraction a destination. Without that structure, extracting information faster does not resolve the separate problem of assembling a consistent memo. With it, the workflow removes re-entry between heterogeneous source documents and the standardized model.
Automated spreading then reduces the work of extracting financial statement figures and constructing the memo’s financial section. That changes the analyst’s task at assembly. Instead of building the document through repeated copying and formatting, the underwriter reviews the populated framework and develops the credit assessment, risk grading, and narrative commentary. The useful comparison is therefore not manual prose versus generated prose. It is repeated document construction versus structured assembly with a defined human review layer.
Extraction quality still depends on source quality. Clean, standardized documents support stronger accuracy, while poor scans, handwritten annotations, and unusual statement formats reduce it. The appropriate design directs analysts to flagged fields, eliminating the need to re-enter every field. Emerging agentic platforms extend this approach across multi-step workflows, including document ingestion, template population, DSCR and LTV calculations, covenant flagging, and post-close monitoring. For these platforms to help, they need the same controlled fields and rules for what people must review as basic extraction.
The objection worth taking seriously: what systematization does not replace
The strongest objection is that a polished, systematized memo can make an unsupported conclusion look settled. If a team accepts AI-generated outputs without rigorous review, model assumptions can enter credit decisions as though they were facts. Formatting consistency does not establish credit validity. Nor does an accurately extracted figure establish that the resulting loan structure is appropriate. A framework that conceals those distinctions produces confident errors.
Extraction, field population, formatting, version control, and lifecycle continuity are mechanical tasks that the system can handle, with stronger extraction accuracy on clean documents. Risk grading and collateral adequacy require underwriting judgment. So do credit policy exception analysis, loan structure decisions, and the narrative assessment of sponsorship quality. Automating the mechanical layer does not transfer authority over those decisions to the template.
The design implication is to separate populated information from authored analysis. Flagged fields require analyst sign-off, and the underwriter writes the credit narrative rather than accepting a narrative generated from the template. The structure supports judgment without supplying it. That boundary also explains why systematization need not flatten differences between deals, because a common framework leaves room for different assessments and conclusions. By removing reconstruction and formatting work, a well-designed system lets senior underwriters concentrate their time where their expertise is indispensable.
What separates teams that scale their memo process from teams that stay stuck
Repeated transactions make the organizational difference visible beyond a single faster closing. A team with a governed framework keeps its section structure, input map, extraction workflow, and loan-type modules for the next deals. A team rebuilding each memo does not accumulate that advantage. At extension or refinancing, prior work provides a structured starting point for teams with a governed framework and another set of documents to interpret for teams rebuilding each memo. Reuse increases process capacity while reducing repeated individual effort.
That capacity supports granular portfolio visibility, standardized documentation, and policy-aligned controls without making every increase in volume depend on a proportional increase in analyst headcount. The benefit extends to the counterparty’s experience. When lenders keep receiving well-organized packages with figures that agree, they gain confidence in the sponsor’s or broker’s ability to execute across transactions. Faster processing and repeat business follow from the pattern. The memo system makes that pattern repeatable while preserving underwriter responsibility for the credit.
The current combination of active originations, deferred maturities, easing standards, and selective lending makes delay costly. Teams that postpone the infrastructure decision continue spending scarce analytical capacity on rebuilding work, leaving less available to evaluate the next transaction. Their competitors can devote more of that capacity to credit assessment and execution. In a high-volume, selective market, the team that consistently delivers sound analysis in a complete, credible package is better positioned to win the next mandate.